Amazon (AMZN -2.25%) is one of the more recognizable stocks in the market, mainly because nearly everyone has used its services at one time or another. However, the market isn't in love with the stock right now, as it's down more than 10% from its all-time highs.
This is a bit suspect, as it reached a new all-time high the last time it reported quarterly earnings in late July. Nothing has changed between now and then, so it could be a case of the market taking profits and moving elsewhere. However, I think that's a huge mistake, as Amazon is right at the beginning of a new growth paradigm.
Image source: The Motley Fool.
Amazon's growth rate is only going to ramp up
When you hear Amazon, the first thing you think of is its commerce and delivery platform. While that's the most consumer-facing portion of Amazon's business, it's far from the best reason to invest in it. Instead, I'd point to cloud computing and advertising as being the best reasons to pick the stock.
Cloud computing is a massive and growing portion of Amazon's business. During Q2, it accounted for about 21% of total sales but 60% of operating profits. AWS is a major beneficiary of the AI build-out, as AI firms and start-ups are looking for places to rent AI training and inference capacity, and Amazon has become a go-to vendor for many of these applications. It's the largest cloud computing provider and is investing $220 billion in capital expenditures this year to expand its footprint.

NASDAQ: AMZN
Key Data Points
However, that's not enough. AWS won't have enough demand to handle 2026 computing demands and likely won't again in 2027. As a result, demand for 2028 is already starting to pop up. That should show investors how in-demand cloud computing is, and with Amazon investing hundreds of billions in this segment, it will drive massive growth for the foreseeable future.
Another major segment that investors gloss over is Amazon's advertising segment. While it isn't as front-facing as AWS, as it's counted for in Amazon's commerce division, it is a major contributor. During Amazon's Q2, advertising grew at a 26% pace -- a rapid acceleration from previous quarters. Unfortunately, Amazon doesn't break out this segment's profitability, but looking at industry peers suggests it likely has a very healthy profit margin, which is why Amazon's commerce segment is as profitable as it is.
These two divisions are what really drive Amazon's future, and with each seeing its growth rate accelerate in the recent quarter, it's a positive sign for investors. However, the stock is down, which could be a great opportunity to scoop up some Amazon stock at a discount.
Amazon's stock isn't too expensive
Amazon is a major investor in Anthropic, which has skewed its EPS metric, as it is required to report a gain on investment even if it doesn't sell its stake, making the price-to-earnings ratio misleading. So I'll go one line item up on the income statement and utilize its operating income to value the stock.
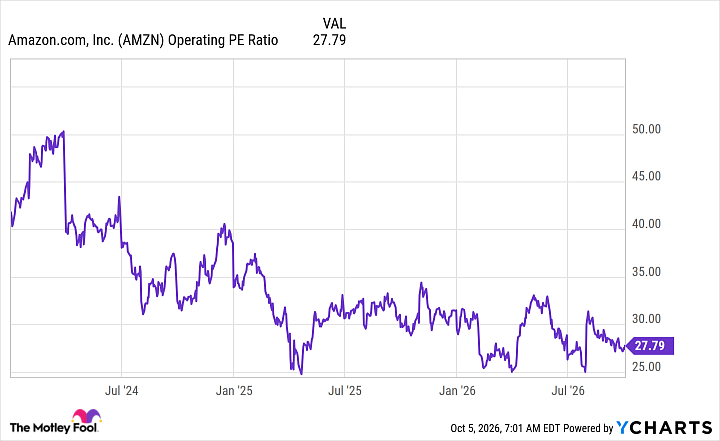
AMZN Operating PE Ratio data by YCharts
Amazon's price-to-operating-income ratio is among the lowest the stock has seen over the past two years, making it attractive. However, Amazon is about to enter one of its fastest-growing segments it has experienced over the past few years, so this price tag is actually far cheaper than it appears.
As a result, I think investors should take advantage of this sale price, as it may not last long once Amazon's Q3 results are out later this month.