Amazon (AMZN +3.29%) and Alphabet (GOOG +0.87%) (GOOGL +0.97%) are two of the biggest spenders in the artificial intelligence (AI) industry. Each has a sprawling cloud computing business with far more demand than capacity, so they're spending unprecedented amounts of money to expand their data center footprints.
For 2026, Amazon plans to spend about $220 billion on capital expenditures, while Alphabet expects to lay out about $200 billion. Nearly all of that will go toward building out data centers.
While I think both stocks are strong investments, I believe Amazon has far more to gain. But don't sleep on Alphabet, as it's growing at an incredibly fast rate.
Image source: Getty Images.
AWS is a major part of Amazon's overall picture
The reason why I think Amazon has more to gain from its cloud computing investment is the position of Amazon Web Services (AWS) within Amazon as a whole. In Q2, AWS accounted for about 21% of Amazon's total revenue. However, AWS produced 60% of Amazon's operating profits.
That's a natural result of the fact that e-commerce and retail generally are relatively low-margin businesses; AWS' operating margin is far higher. This magnifies the effect that revenue growth from AWS has on the overall company's profitability. So its net sales rose 20 year over year in Q2, but its operating income increased by 43%. As Amazon continues to invest big time in AWS, its added capacity will translate directly into impressive revenue growth and even larger profit growth.

NASDAQ: AMZN
Key Data Points
Likewise, Alphabet is benefiting from Google Cloud's growth, but not to the same degree. The company's core business is advertising from its Google family of products, and that already has a pretty strong operating margin.
Companywide, Alphabet had an operating margin of 34% in Q2. Google Cloud did slightly better, with a 36% operating margin, but since it's already pretty close to the company's overall margin, it doesn't have the outsized effect on profits that AWS has on Amazon.
But don't disregard Google Cloud, either. Google Cloud's revenue growth in Q2 was 82% year over year, while AWS's was 37%. That mismatch shows how Alphabet is rapidly expanding its cloud segment. However, it's doing so off a much smaller base. Amazon is the world's largest cloud infrastructure provider, with a 28% market share as of Q2. While No. 3 Alphabet is slowly cutting into that lead, it still accounts for just 15% of the market. Google Cloud booked $24.8 billion in revenue in Q2, while AWS booked $42.2 billion.

NASDAQ: GOOG
Key Data Points
While AWS' margins may have a bigger impact on Alphabet's bottom line, Google Cloud's pure growth nearly overcomes that advantage. As a result, I think both of these stocks could be excellent buys, as each has something special going for it in the cloud segment. And given the scale of their spending to expand their respective cloud segments, there's a lot more growth to come for each of them.
But is there a discrepancy that an investor can take advantage of from a valuation perspective?
Amazon and Alphabet trade at about the same valuation
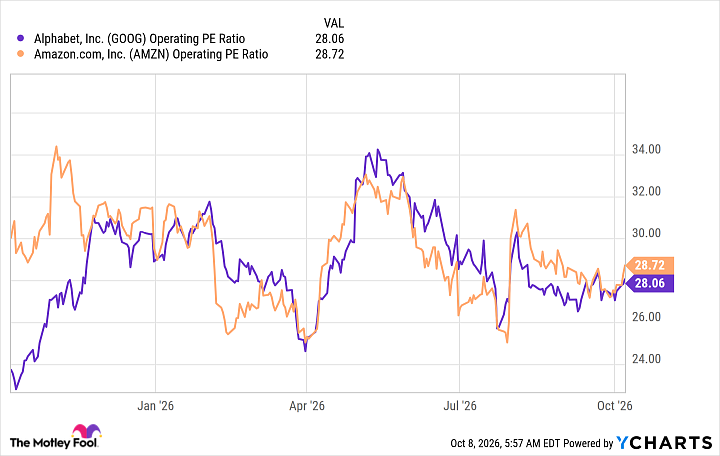
Both Amazon and Alphabet have seen several of their investments in outside companies rise in value recently, so their earnings per share metrics are skewed by these gains. Measuring them based on their operating profits strips out the impact of those gains.
GOOG Operating PE Ratio data by YCharts.
Ever since Alphabet's rally started last year, these two have traded at nearly the same operating P/E ratio, and that's still the case today. As a result, there isn't much of an advantage to choosing one or the other based solely on valuation.
So if you're trying to pick between them as investments, the choice boils down to personal preferences and whether you prefer raw revenue growth or outsize profit growth. I'm in the latter camp, so I'm choosing Amazon. But this is really splitting hairs -- Alphabet is also a worthy investment.