The S&P 500 hit a fresh record high last week, and it's trading at an elevated valuation as investors price in some very high forward expectations for artificial intelligence (AI) companies. As a result, strong corporate earnings are the key to keeping this bull market going, and most technology giants will report their latest quarterly results over the next month.
Google parent Alphabet (GOOG -1.68%)(GOOGL -1.74%) is scheduled to release its operating results for the third quarter (ended Sept. 30) on Oct. 28. Its stock happens to be reasonably valued heading into the report, and here's why I predict it could soar in the weeks and months that follow.
Image source: Alphabet.
Wall Street will be focusing on Google Search and Google Cloud
Alphabet is an incredibly diverse tech conglomerate, but Google Search and Google Cloud are currently its most important businesses. Search accounts for more than half of the company's total revenue, whereas Cloud is the fastest-growing segment.
There were some concerns that AI chatbots would disrupt traditional internet search engines like Google Search, but Alphabet introduced a series of AI features to transform the user experience. AI Overviews, for instance, use text and images to provide AI-generated responses to queries, which appear above the traditional search results. Then there is AI Mode, which opens a chatbot-style interface where users can expand on their original queries by asking additional questions.
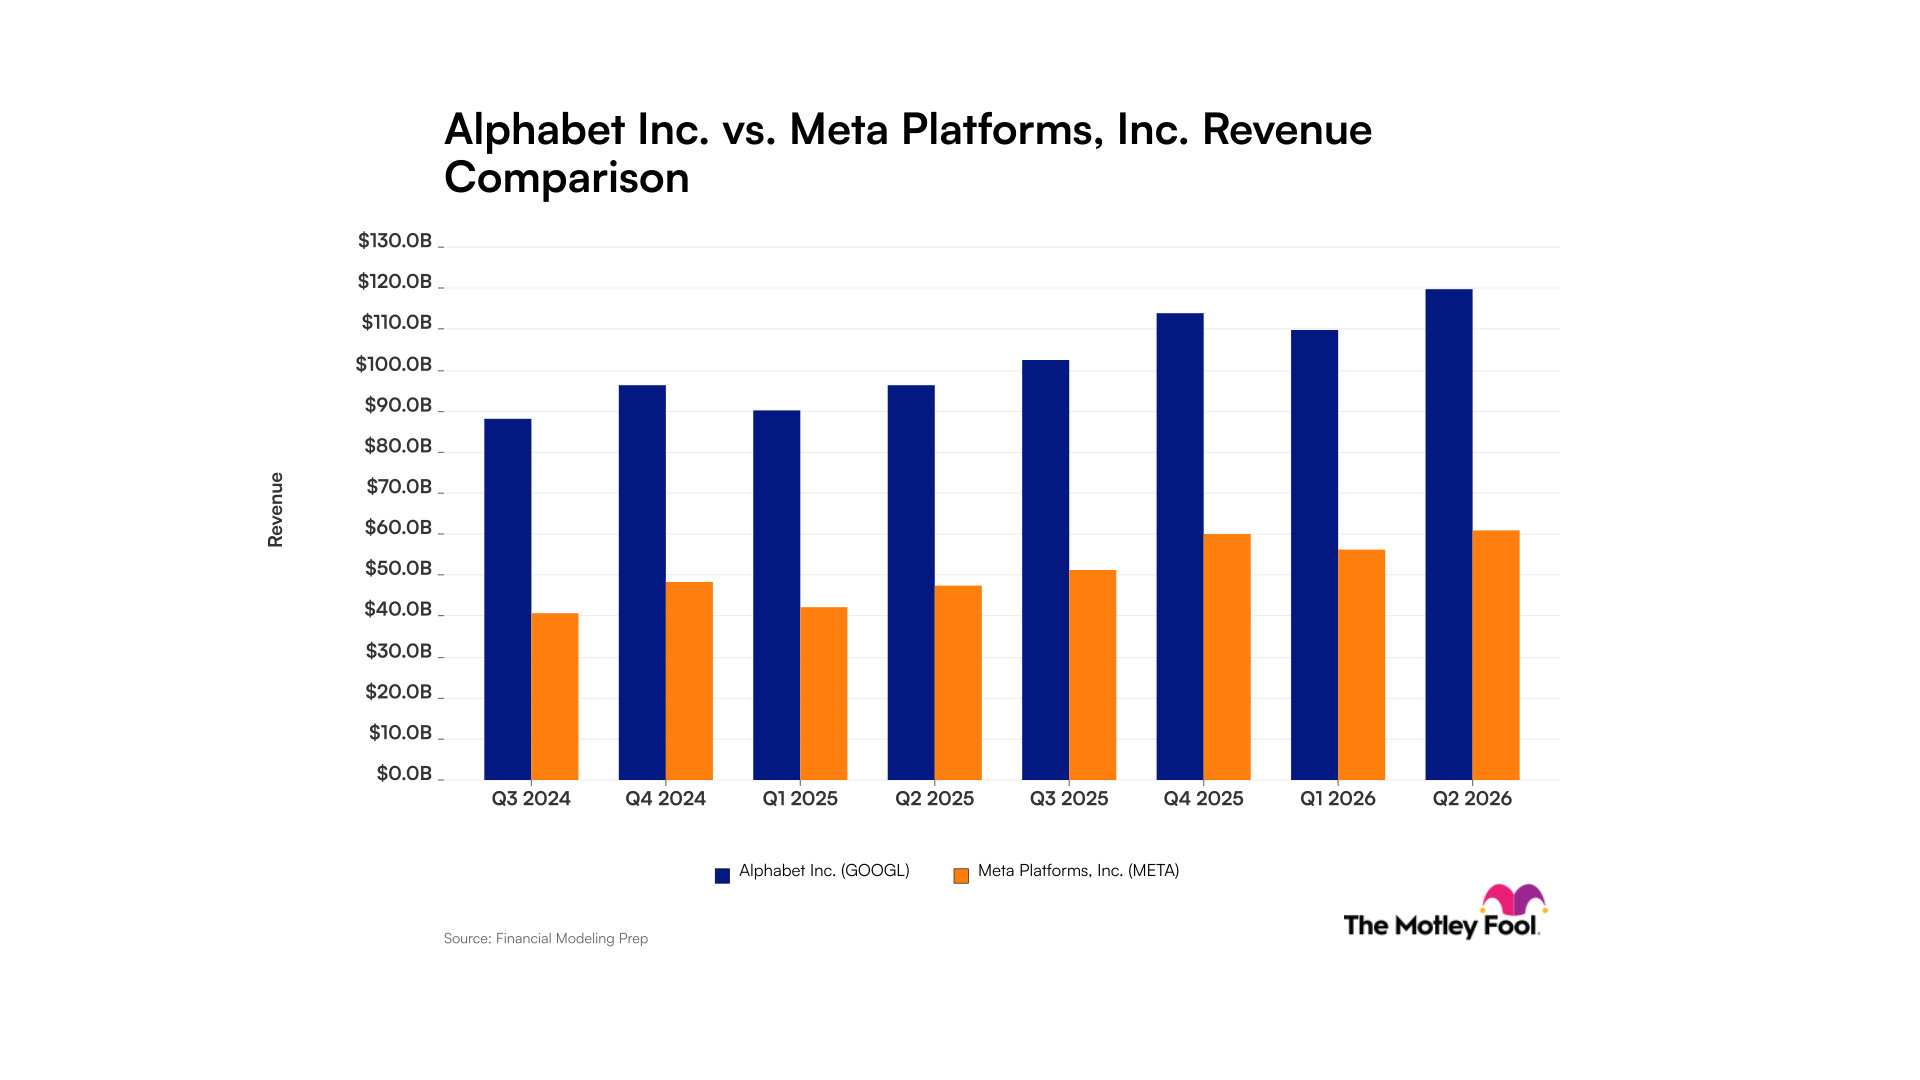
During Alphabet's last quarterly conference call, CEO Sundar Pichai said AI Mode had surpassed 1 billion monthly users, and that these new features were driving an increase in Google Search usage overall. This means users are seeing more ads, which is why the platform generated a record $63.3 billion in revenue during the second quarter (ended June 30), up 17% year over year. Investors should look for a fresh update on how AI is improving the search business on Oct. 28.
Google Cloud is also coming off a record second quarter with revenues of $24.8 billion, which represented an accelerated growth rate of 84%. The platform provides its enterprise customers with access to computing capacity from state-of-the-art data centers, and a suite of ready-made foundation models, which are the primary ingredients for developing AI software. As of June 30, Google Cloud had a staggering $514 billion order backlog from customers who were waiting for Alphabet to build more AI infrastructure.
The backlog might be a good predictor of future revenue, so it's one of the main numbers Wall Street analysts will be looking at on Oct. 28. If it increased during the third quarter, it will be a sign that demand for AI computing capacity remains very strong.
Alphabet stock looks attractive heading into Oct. 28
Alphabet's second-quarter earnings soared by 294% year over year to $9.11 per share, mostly because of the Space Exploration Technologies (SPCX -2.80%) initial public offering (IPO) in June. Alphabet invested $900 million in SpaceX through a private placement in 2015, but accounting rules required the company to recognize the fair market value of its position after the IPO, which was over $90 billion as of June 30. Hence, there was a huge one-off increase to Alphabet's earnings, which had nothing to do with its operating performance.
With that out of the way, Wall Street's average estimate (provided by Yahoo! Finance) suggests Alphabet's earnings likely stabilized at around $3.02 per share in the third quarter, representing a more modest year-over-year growth rate of 5%.

NASDAQ: GOOGL
Key Data Points
It's disingenuous to value Alphabet based on its trailing-12-month earnings because of the inflated second-quarter result. But looking ahead, Wall Street thinks the company will generate earnings of $14.98 per share during 2027, placing its stock at a forward price-to-earnings (P/E) ratio of 23.4. That represents a slight premium to the Nasdaq-100 index which has a forward P/E of 22.1, but I think it's justified given the incredible AI-related strength in Google Search and Google Cloud.
Alphabet stock has returned around 45% over the past 12 months, but I think the company's third-quarter report will lay the groundwork for the next leg of upside, as long as its operating results show further momentum in the search and cloud businesses.