When you ask the average person about Amazon (AMZN -2.24%), they'll undoubtedly talk about its online store. While that may be the largest consumer-facing segment of Amazon, it's far from the best division. That title belongs to Amazon Web Services (AWS), which has been one of the biggest beneficiaries of the ongoing AI build-out.
AWS' margins are booming, and there's plenty more work ahead. I think that's a recipe for the stock to skyrocket.
Image source: The Motley Fool.
You have to spend money to make money
Amazon is no stranger to spending money to build out its operations. It was unprofitable for years as it worked to establish its e-commerce business and build the massive infrastructure required to support it. While Amazon is profitable now, it's using all of its cash flow to build out its AI data center footprint. In fact, it's on course to spend around $220 billion this year on capital expenditures, with nearly all of that total going to data centers.

NASDAQ: AMZN
Key Data Points
Many investors may be concerned that it's spending so much. But when you dig in, it's clear there's a generational opportunity here.
At its core, AWS is a rental business. Amazon builds out computing capacity, then leases access to this computing capacity to its clients. There has never before been a time when so much new demand for computing capacity arrived so rapidly, and Amazon and its cloud computing peers don't have nearly enough to meet it. Amazon's backlog is nearly $500 billion, and it's increasing at a triple-digit percentage rate year over year despite how much it has already built. A host of cloud providers are spending big to get new data centers online, but new AI workloads continue to appear, pushing demand higher.
This is leading to AWS' revenue growth rapidly accelerating.
AWS' financial profile is getting better
For most of 2025, AWS' growth rate was somewhere in the lower 20% range. In the second quarter of 2026, it accelerated to 37% year over year. AWS' operating margin also improved, rising to 39%. That's a big deal, because AWS' operating margin is far better than that of the company's commerce segments. In fact, AWS accounted for 60% of Amazon's operating profits in Q2.
While this may sound impressive for one quarter, investors can expect many more like it. Amazon is spending heavily on data centers and has a massive backlog of business to convert into revenue. AI inference workloads run more or less continuously, creating a recurring revenue stream for Amazon. The market gains the company is making now will have a real and tangible effect on its operating picture years from now, so it must seize as much market share as possible during this phase of the trend. It's doing just that while expanding its AWS platform.
This could lead to huge growth for Amazon over the next few years, and not all of that potential is reflected in its stock price.
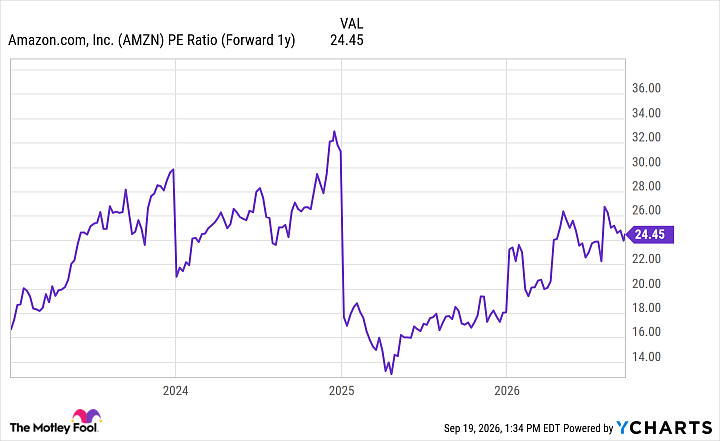
AMZN PE Ratio (Forward 1y) data by YCharts.
Trading at less than 25 times next year's expected earnings, Amazon's stock looks like it's priced right to continue a strong run for the foreseeable future. Amazon has never been a cheap stock historically, and with performance like it's expecting, I doubt it will ever get that way. The AI infrastructure build-out is also far from over, and Amazon made some noteworthy comments regarding that as well. CEO Andy Jassy told investors that it wouldn't be able to build computing capacity fast enough to fully meet demand in 2026, and the shortage will likely persist through 2027. As a result, it's already seeing 2028 demand pop up. That bodes well for the future, and with this phase of the AI race not expected to conclude until at least 2030, Amazon is in the driver's seat to deliver huge returns.
As a result, I think Amazon is a perfect stock to scoop up right now.