The U.S. is home to 13 public companies worth $1 trillion or more, but only Nvidia, Alphabet, Apple, and Microsoft are worth over $3 trillion as I write this (Sept. 22).
I predict Meta Platforms (META +1.02%) will join that exclusive club within the next couple of years, thanks to its aggressive investments in artificial intelligence (AI). Earlier this month, the company launched a personalized AI agent called Muse that can perform tasks outside of its Facebook, Instagram, and WhatsApp social media applications.
Muse's surging popularity has whipped investors into a frenzy, sending Meta stock soaring by 11% on Monday alone. The company now has a market capitalization of $1.91 trillion, and here's how it could join the $3 trillion club.
Image source: Getty Images.
Muse marks the start of a new era for Meta
Around 3.6 billion people use at least one of Meta's social media apps every single day. Since there are only 8.3 billion people on Earth and the company's apps are blocked in China, it's getting harder to find new users. Therefore, Meta is now more focused on keeping existing users online for longer periods of time, so they see more ads and generate more revenue for the company.
So far, Meta has achieved this by integrating AI into its recommendation algorithms to learn what content each user likes to see on Facebook and Instagram, so it can show them more of it. These algorithms will only grow more accurate with time, because they are constantly learning and evolving.
But during his conference call with shareholders for the second quarter of 2026 (ended June 30), chief executive officer Mark Zuckerberg explained that AI agents could eventually transform the social media experience by assisting users with every part of their lives. The company proceeded to launch the Muse AI agent on Sept. 8, which is designed to do exactly that.
Muse can tap into almost any third-party app (with permission), so it can help the user write emails, book a vacation, shop online, and more. Muse even integrates with a digital wallet called Link, which was built by Stripe, so it can make payments at the user's request. This agent gives Meta an opportunity to capture a much bigger share of global internet traffic. The company isn't competing with just other social media giants anymore, but also entrenched platforms such as Google Search.
Muse has its own mobile app, and it operates through its own secure virtual machine that stores all of its data. It also conducts internet searches with its own internal browser, so it's one of the safest agents on the market right now.

NASDAQ: META
Key Data Points
AI spending could be a headwind for Meta's earnings in the coming years
Muse was built from the ground up on an entirely new family of foundation models called Muse Spark. These differ from Meta's Llama family of open-source AI models, which have been downloaded over 1 billion times. The company wanted the Muse agent to have its own identity, but more importantly, it also wanted to prioritize security.
Unfortunately, it's incredibly expensive to develop AI models. Meta spent $72 billion on data center infrastructure in 2025 to ensure it had enough computing power to achieve its goals. The company's latest guidance suggests spending could double to $145 billion during 2026, and there is no apparent plan to slow down.
Meta can't deduct these capital expenditures up front because data centers have a useful life of several years, so it depreciates the infrastructure over time instead. In practice, that means the company's spending in 2025 and 2026 could negatively impact its earnings in 2027, 2028, 2029, and beyond, so generating a return on AI products like Muse is absolutely critical.
Wall Street's average forecast (provided by Yahoo! Finance) suggests Meta could grow its revenue by 20% to $306 billion in 2027, which would be a solid result. However, its earnings are expected to increase by just 8% to $33.87 per share, as its data center spending starts to take a toll on the bottom line.
Meta has a mathematical path to the $3 trillion club
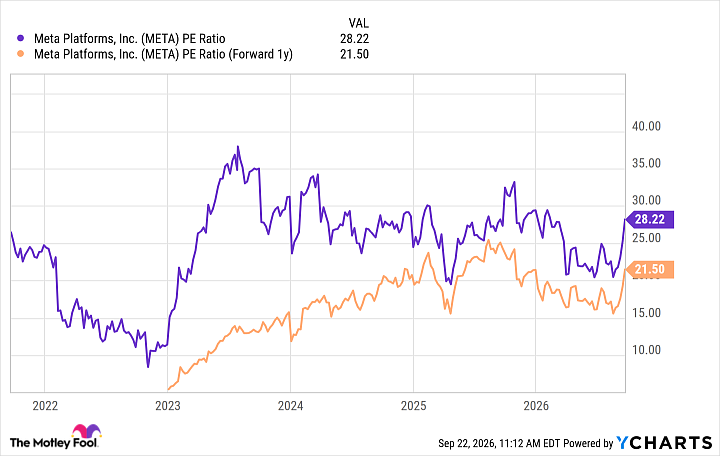
Meta can still reach the $3 trillion club within a couple of years, despite the earnings headwind. Based on the company's trailing 12-month earnings of $26.55 per share, its stock is trading at a price-to-earnings (P/E) ratio of 28.2, a considerable discount to the Nasdaq-100 index, which has a P/E of 34.1. In other words, Meta looks undervalued compared to a basket of America's leading tech giants.
Looking ahead, if we assume Meta's earnings come in at $33.87 per share next year as Wall Street expects, then its stock has a forward P/E ratio of just 21.5. That suggests the stock will have to climb by 59% before the end of next year just to match the current P/E of the Nasdaq-100 -- resulting in a market cap of $3 trillion.
META PE Ratio data by YCharts
Even if Meta's P/E remains at a discount to the P/E of the Nasdaq-100, it could still achieve a $3 trillion market cap sometime in 2028 by simply generating moderate earnings growth.